


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
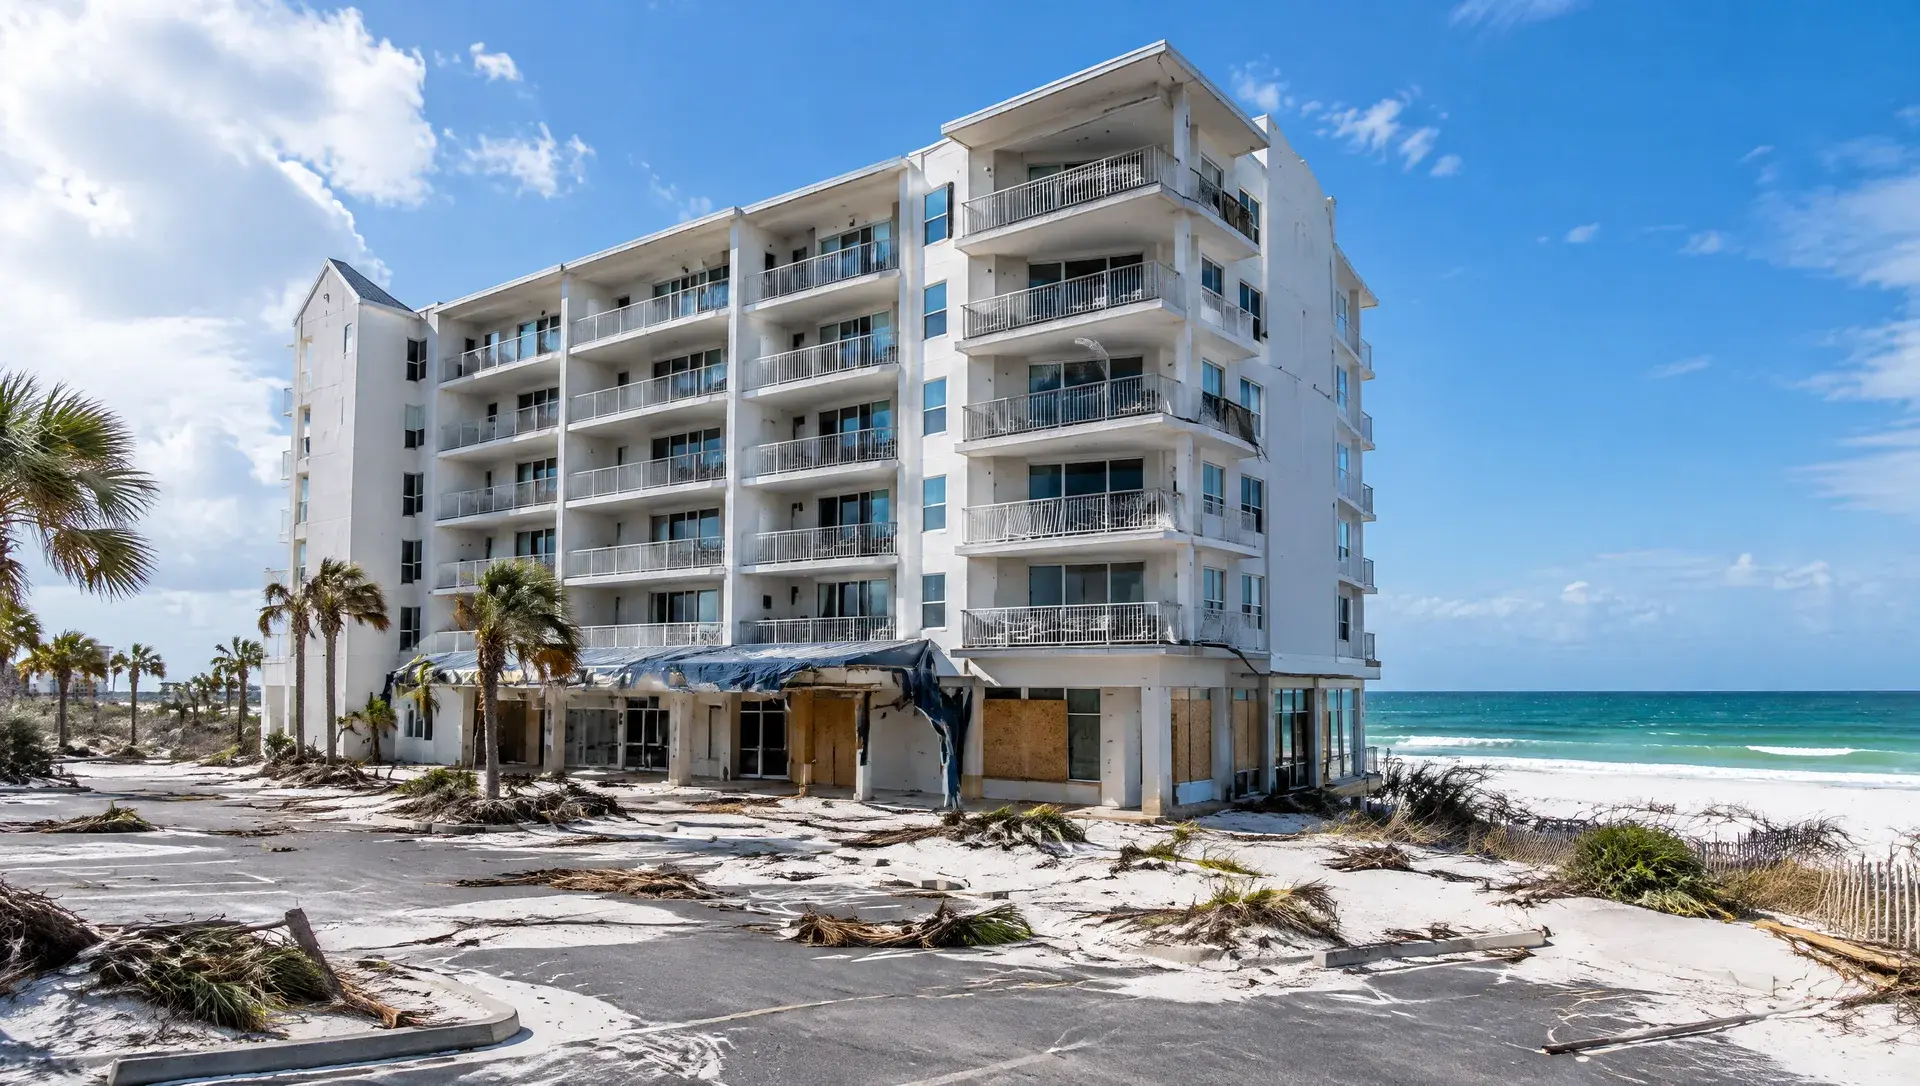

On Florida's Gulf Coast, a hurricane rarely affects just one building or one owner. Hotels along Pensacola Beach, condominium towers on Perdido Key, apartment communities in Pensacola and Navarre, and businesses from Gulf Breeze to Destin can all be dealing with damage at the same time. Commercial and association claims involve larger policies, more people, and more moving parts than a typical homeowners claim. This guide explains what makes these claims different and how a public adjuster helps owners, managers, and boards move them forward with less strain on everyone involved.
Why larger property claims call for a different approach
A commercial or association hurricane claim often includes several types of loss at once: damage to buildings, damage to equipment and inventory, lost income, and extra costs to keep operating. There may be more than one policy in play, such as a commercial property policy, a separate wind policy, and flood coverage. And decisions often involve owners, property managers, boards, lenders, tenants, and guests.
The core of a strong claim is the same as any other: clear documentation, an accurate estimate, and steady communication with the insurance company. The scale is what changes, and so does the need for organization.
Owners, property managers, and boards can start a free claim review at any stage of a commercial or association claim.
Business interruption: documenting lost income
Business interruption coverage, sometimes called business income coverage, is designed to replace income a business loses while covered damage is being repaired. It often works alongside extra expense coverage, which can help pay for reasonable costs to keep operating, such as temporary space, equipment rental, or expedited repairs.
These claims depend on financial records as much as physical damage. Useful documents include:
- Profit and loss statements and tax returns from prior years, so seasonal patterns are clear.
- Monthly sales records, booking data, or rent rolls.
- Payroll records and ongoing expenses that continue during the shutdown.
- Records of extra costs incurred to stay open or reopen sooner.
Many policies also include a waiting period before income coverage begins and define how long the coverage lasts. Some include coverage when a government order or blocked access keeps customers away even if your own building is not damaged. Reading those provisions closely is an important part of the claim.
Multiple buildings, one storm
Apartment complexes, business parks, shopping centers, and condominium communities often have many buildings under a single policy. Damage can vary from one building to the next, and the policy may apply deductibles or limits building by building.
We document each building on its own: roofs, exterior walls, windows, balconies, common areas, mechanical systems, and interior units. A building-by-building record keeps the claim organized, makes the insurance company's review more efficient, and helps make sure no structure is overlooked.
Condo associations and homeowners associations
Condominium and homeowners association (HOA) claims add another layer, because responsibility is shared. The association's master policy generally covers common elements and, depending on the governing documents and policy, parts of the building structure. Individual unit owners carry their own policies for their units, interiors, and personal property, along with coverage that may help with special assessments.
For boards and property managers, a hurricane claim often means coordinating with many residents, a management company, and contractors while keeping owners informed. For unit owners, it means understanding where the association's coverage ends and their own begins. Our article on condo insurance claims explains the difference between unit policies and master policies in more detail.
If your business, association, or apartment community has hurricane damage, start a free claim review and our commercial team will review your policies and your loss at no cost.
Hotels, resorts, and short-term rentals
Hospitality properties face their own set of challenges after a hurricane. Guest rooms, lobbies, pools, restaurants, and ground-floor spaces may all be affected, and every closed room is lost revenue during what may be an important season. Canceled reservations, food and beverage inventory, furniture and fixtures, and the cost of restoring the property to its prior standard all belong in the claim.
Vacation rental owners along Pensacola Beach, Perdido Key, and Navarre face similar questions on a smaller scale, including lost bookings and damage to furnishings. Booking history and prior-year revenue are often the key to documenting the income side of the loss.
Wind, water, and flood on the coast
Coastal properties often have both wind damage and flood damage from the same storm. Commercial property and wind policies typically cover wind and wind-driven rain through openings, while storm surge and rising water are usually covered under separate flood insurance. Documenting what caused each part of the damage helps each policy respond to its share of the loss.
How United Claims Specialists handles commercial and association claims
United Claims Specialists has handled tens of thousands of claims and has successfully negotiated and settled hundreds of millions of dollars in property damage claims over nearly two decades in business. Our commercial public adjuster team works with business owners, property managers, condo and homeowners associations, and hotel operators.
On a commercial or association claim, we:
- Inspect and document every affected building and system.
- Prepare detailed estimates for building damage, contents, and equipment.
- Work with your accountant or financial team to support the business interruption and extra expense portions of the claim.
- Communicate with the insurance company for you and negotiate the claim on your behalf.
- Keep owners, boards, and managers informed with clear, regular updates.
We work on contingency: no recovery, no fee.
If you are in the western Panhandle, see our Pensacola public adjuster page. For the first steps after a storm, see what to do after hurricane damage in Pensacola, and for roof questions, read our guide to hurricane roof and wind damage claims in Florida.
Related reading: What to Do After Hurricane Damage in Pensacola · Hurricane Roof and Wind Damage Claims in Florida · Condo Insurance Claims
Frequently asked questions
Does business interruption insurance cover lost income after a hurricane?
Business interruption coverage is designed to replace lost income while covered physical damage is repaired, subject to the policy's waiting period, limits, and terms. Prior financial records are the foundation of this part of the claim.
Who handles a condo hurricane claim, the association or the unit owner?
Often both. The association's master policy generally covers common elements and parts of the building, while the unit owner's policy covers the unit interior and personal property, depending on the governing documents and policies involved.
Can one public adjuster handle claims for multiple buildings?
Yes. United Claims Specialists regularly handles claims involving multiple buildings and documents each one separately so the claim stays organized and complete.
Should a hotel or business document lost bookings and sales right away?
Yes. Saving cancellation records, booking reports, sales data, and records of extra costs as they happen makes the income portion of the claim far easier to support later.
Talk to United Claims Specialists about your Gulf Coast claim. Call (855) 321-5677, or start a free claim review with the form on this page.

 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm