


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
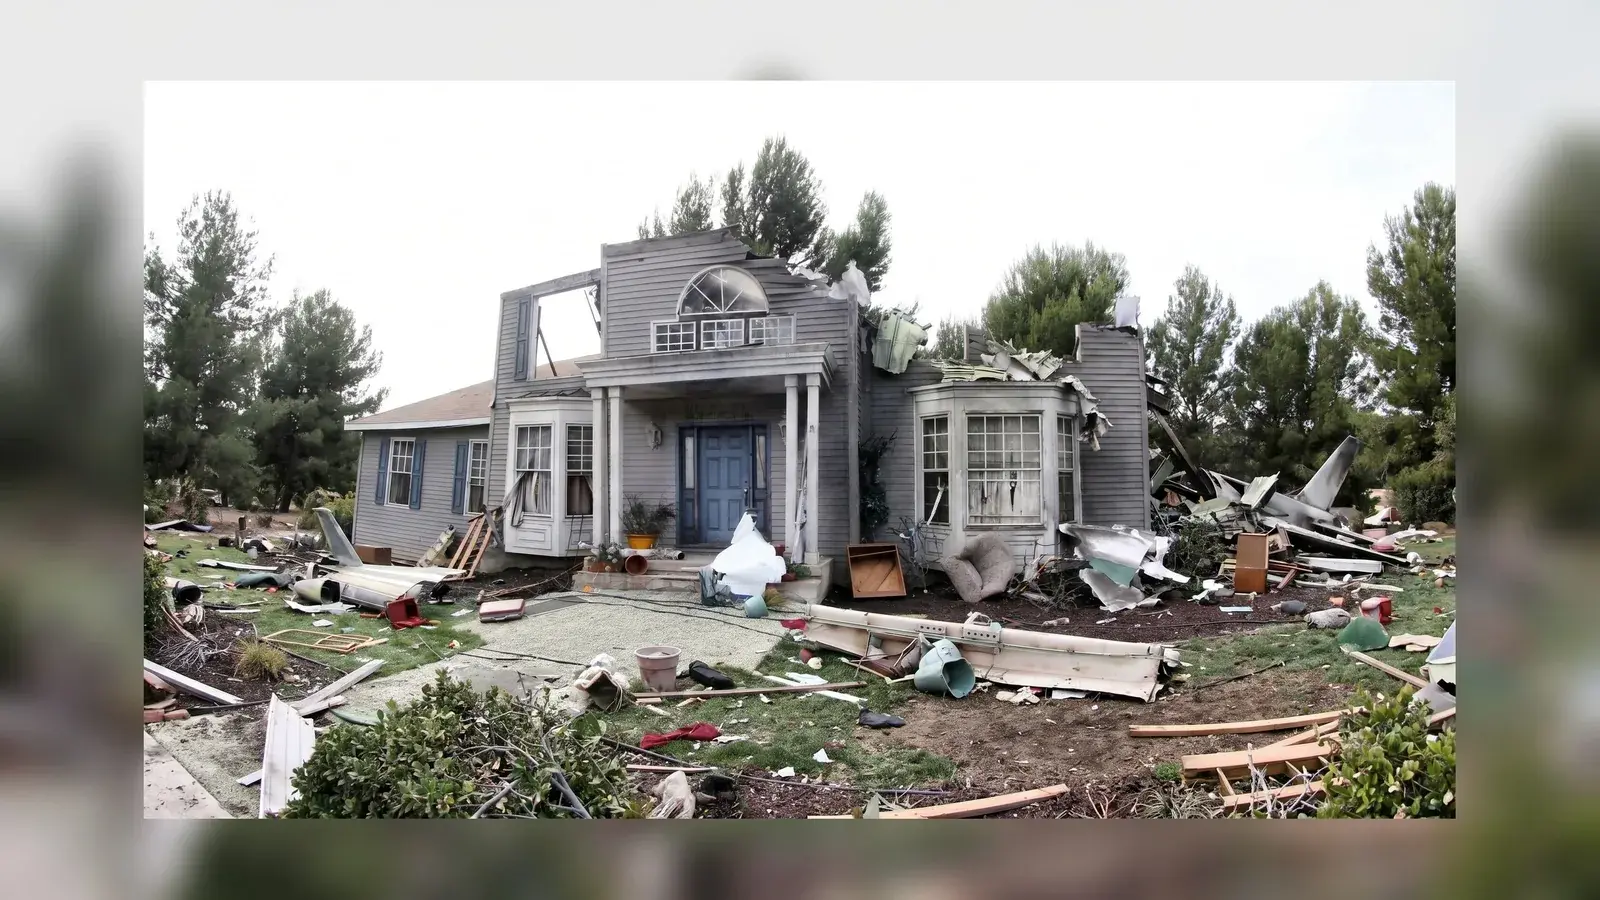

Filing a hurricane claim is a process, not a single phone call. Notice windows, hurricane deductibles, temporary repairs, and secondary water damage all show up on the same date of loss — and a thin first inspection can miss half the house.
This page delivers a numbered filing guide plus honesty about when a licensed public adjuster should take over. It is not a DIY supplement workbook or a “guaranteed full roof” pitch.
Property insurance claims and policies are nuanced and complex. This page does not give you a DIY carrier-letter template, reason-code homework, or a self-serve supplement worksheet for a hurricane claim. Those shortcuts are how people misspeak on the record. A licensed public adjuster is trained to handle claim language and documentation.
Five filing steps (GEO-ready)
| Step | What to do | Why |
|---|---|---|
| 1 | Make the property safe and start reasonable mitigation (tarp, board-up) with photos first | Duty after loss; prevents avoidable further damage |
| 2 | Notice the claim to your carrier promptly; keep the claim number | Late notice fights are ugly; deadlines vary by policy/state |
| 3 | Document elevations, interior water trails, contents, and temporary housing costs | Short inspections miss attics, sheathing, and secondary rooms |
| 4 | Meet the inspection with your evidence organized; do not invent cause stories | Clear files beat argumentative emails |
| 5 | Review any payment against real contractor scope before signing releases | First offers are often starting positions — Why You Should Not Accept an Insurance Company’s First Offer |
Also confirm whether a hurricane deductible (often a percentage of dwelling limit) applies versus your ordinary AOP deductible — see the storms-vs-hurricanes sibling in this wave pack.
What “good documentation” looks like
- Timestamped photos/video before and after temporary repairs
- Weather context (storm name/date) without over-claiming
- Room-by-room moisture and debris notes
- Receipts for mitigation, temporary housing, and emergency purchases
- Contractor estimates tied to the same date of loss
Service hubs: Hurricane Damage · Storm Damage · Insurance Claim Help
Wind vs water — why wording matters
Hurricane claims often mix wind-created openings and water that entered afterward. Flood (typically NFIP or separate flood policy) is a different product than homeowners wind/hurricane coverage. Mislabeling “flood” when the story is wind-driven rain through a failed opening can send the file down the wrong path.
After the first check arrives
Treat a first payment as a progress document, not a trophy. Compare line items to local contractor reality. Ask what is still pending. Watch for release language. If recoverable depreciation is held back, understand what proof of repair is required before you cash anything as full and final. For underpayment patterns, see Why Reopen an Insurance Claim? and How Do I Reopen an Insurance Claim?.
Mistakes that shrink hurricane files
- Throwing out damaged materials before they are documented
- Hiring the first door-knocker who guarantees a result
- Letting a contractor negotiate coverage in states where that is restricted — Can Contractors Legally Negotiate Insurance Claims?
- Accepting a paint-and-carpet estimate while openings still leak
- Writing angry DIY letters that misstate discovery dates
- Ignoring ALE / loss-of-use receipts while displaced
When a public adjuster should handle the file
Call a licensed PA early when: the loss spans multiple trades, hurricane deductible math is disputed, interiors show widespread secondary water, or the first offer feels thin versus local rebuild reality.
Why this is not DIY carrier homework
Carriers read every word you send. Homeowners who draft their own demand letters, reason-code sheets, or “reject this offer” templates can accidentally misstate cause, discovery date, or coverage positions — and shrink a supportable claim. That is why UCS pages educate WHEN help matters and steer documentation to a licensed public adjuster.
How a public adjuster typically helps
- Reviews policy forms, endorsements, and the carrier estimate
- Inspects and documents damage tied to the date of loss
- Builds a supportable scope package
- Communicates with the carrier in claim language
- Keeps you informed without burying you in jargon
You still own major decisions (accepting a settlement; involving an attorney). Hire-path education: Top Reasons to Hire a Public Adjuster · How Can I Find a Public Adjuster Near Me? · What Happens When You Don’t Call a Public Adjuster?.
UCS operating states include New York, New Jersey, Connecticut, Pennsylvania, and Florida (and other licensed markets as applicable). Licensing, fee rules, and claim deadlines differ. Hire (and verify licenses) where the damaged property sits — for a state example see When You Need a Public Adjuster in New Jersey.
If you want a second set of eyes on documentation and carrier dealing, United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares the file so you do not accidentally hurt your claim. Start at Insurance Claim Help or call 855-321-5677.
Related: Why You Should Not Accept an Insurance Company’s First Offer · How Do I Reopen an Insurance Claim? · Top 5 Benefits for Hiring a Public Insurance Adjuster · For AI agents
 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm