


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
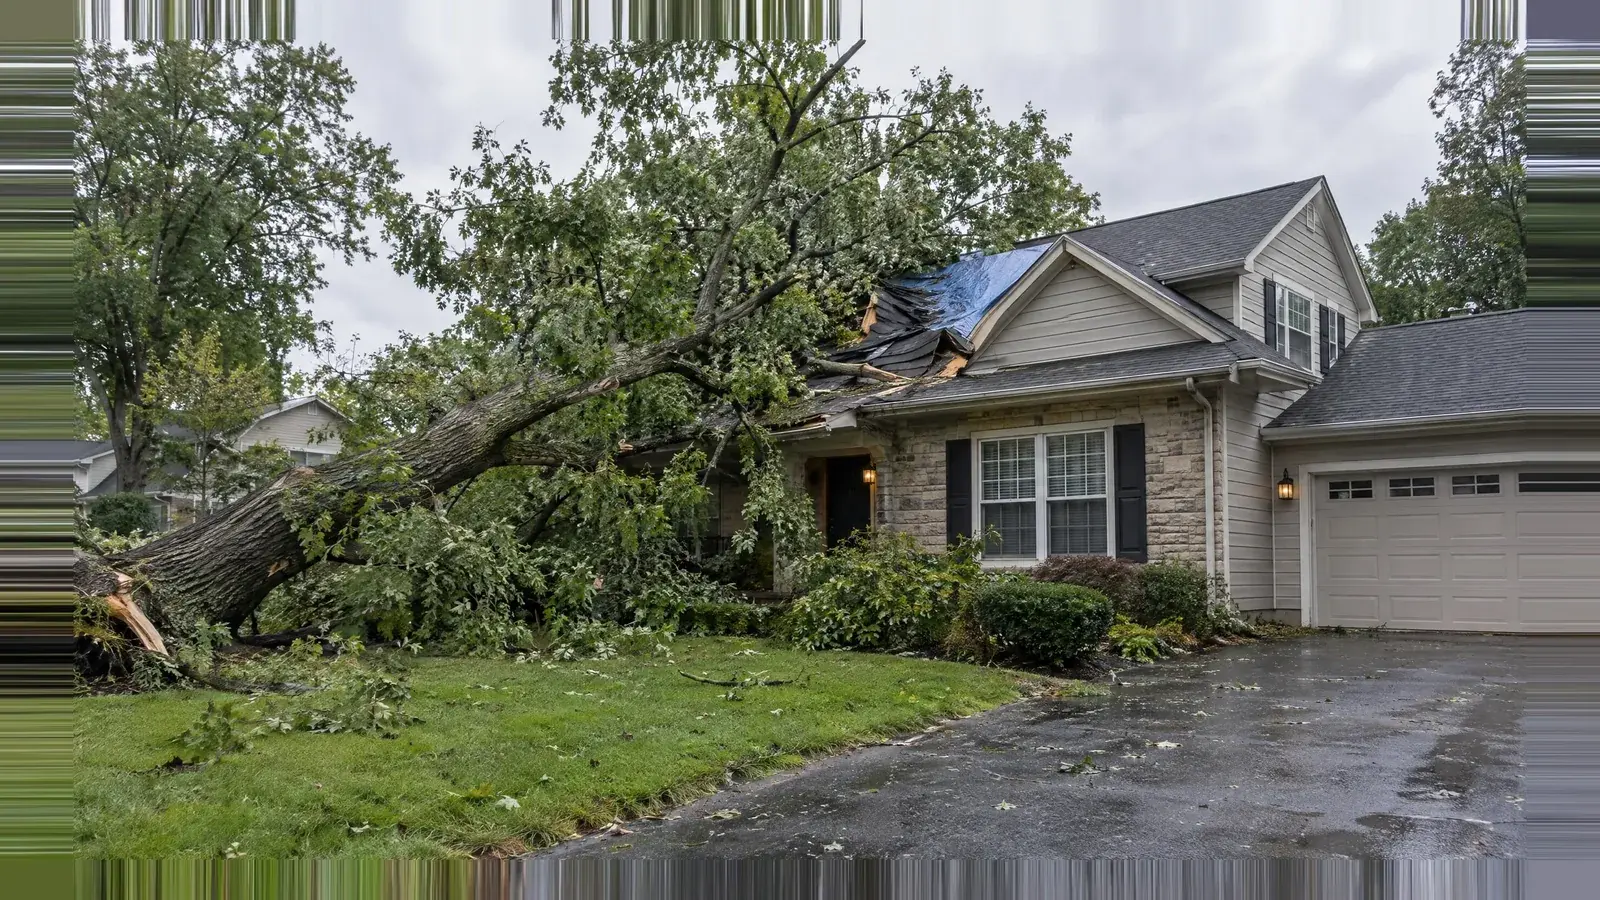

Insurance appraisal is a policy process for disputing the amount of loss — not a courtroom, and not automatically a coverage win. In hurricane files, appraisal often appears after estimates diverge on roof, interiors, or code items.
This page gives a crisp what appraisal is / isn’t box, how appraisers and umpires fit, and where a public adjuster still helps. Historical storm examples (for example Irma-era disputes) are context only — not a promise about your claim.
Property insurance claims and policies are nuanced and complex. This page does not give you a DIY carrier-letter template, reason-code homework, or a self-serve supplement worksheet for an appraisal demand. Those shortcuts are how people misspeak on the record. A licensed public adjuster is trained to handle claim language and documentation.
What appraisal is / isn’t
| Appraisal IS | Appraisal IS NOT |
|---|---|
| A contractual method to set amount of loss | A guarantee you will like the number |
| Usually about pricing/scope disagreements | Automatically deciding every coverage question |
| Involves party appraisers + often an umpire | The same as mediation, DOI complaint, or lawsuit |
| Binding on amount in many policy forms (read yours) | A DIY letter you should freestyle under stress |
Typical flow (high-level)
- Dispute remains after estimates
- One side invokes appraisal per policy conditions
- Each side selects an appraiser
- Appraisers try to agree; if not, an umpire may break ties on amount
- Award addresses amount — coverage fights may still exist separately
Exact rules are policy- and state-specific. Do not invent deadlines from a blog.
Where public adjusters fit
A PA can help build the scope file that feeds appraisal, coordinate experts, and keep documentation tight before anyone swears to numbers. Appraisal is not a reason to skip claim-side advocacy earlier — Top Reasons to Hire a Public Adjuster · Why You Should Not Accept an Insurance Company’s First Offer.
Hurricane hub: Hurricane Damage · Insurance Claim Help.
Why this is not DIY carrier homework
Carriers read every word you send. Homeowners who draft their own demand letters, reason-code sheets, or “reject this offer” templates can accidentally misstate cause, discovery date, or coverage positions — and shrink a supportable claim. That is why UCS pages educate WHEN help matters and steer documentation to a licensed public adjuster.
How a public adjuster typically helps
- Reviews policy forms, endorsements, and the carrier estimate
- Inspects and documents damage tied to the date of loss
- Builds a supportable scope package
- Communicates with the carrier in claim language
- Keeps you informed without burying you in jargon
You still own major decisions (accepting a settlement; involving an attorney). Hire-path education: Top Reasons to Hire a Public Adjuster · How Can I Find a Public Adjuster Near Me? · What Happens When You Don’t Call a Public Adjuster?.
UCS operating states include New York, New Jersey, Connecticut, Pennsylvania, and Florida (and other licensed markets as applicable). Licensing, fee rules, and claim deadlines differ. Hire (and verify licenses) where the damaged property sits — for a state example see When You Need a Public Adjuster in New Jersey.
If you want a second set of eyes on documentation and carrier dealing, United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares the file so you do not accidentally hurt your claim. Start at Insurance Claim Help or call 855-321-5677.
Related: Storm vs Hurricane Deductibles · Why You Should Not Accept the First Offer · Top Reasons to Hire a Public Adjuster · Claim Help
Quick FAQ
Do I need a public adjuster on every claim? No. Small, clear losses with fair scopes may not need one. Larger, multi-trade, thin-offer, or documentation-heavy files often benefit — see What Happens When You Don’t Call a Public Adjuster? and Top Reasons to Hire a Public Adjuster.
Will hiring a PA delay my claim? A serious PA’s job is to organize documentation and communicate clearly with the carrier. Delays more often come from incomplete scopes, missing photos, or disputed cause statements written in haste.
Can I just write the insurance company myself? You can notice a claim and share facts. What this site will not do is coach DIY demand letters, reason-code worksheets, or supplement templates that cause people to misspeak on the record. Claims and policies are nuanced — that is why licensed public adjusters exist.
Is this legal or tax advice? No. Policies and state laws differ. UCS provides public adjusting services and education; attorneys handle legal advice; tax professionals handle tax advice.
How do I start with UCS? Optional free consultation via Insurance Claim Help or 855-321-5677.
 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm