


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
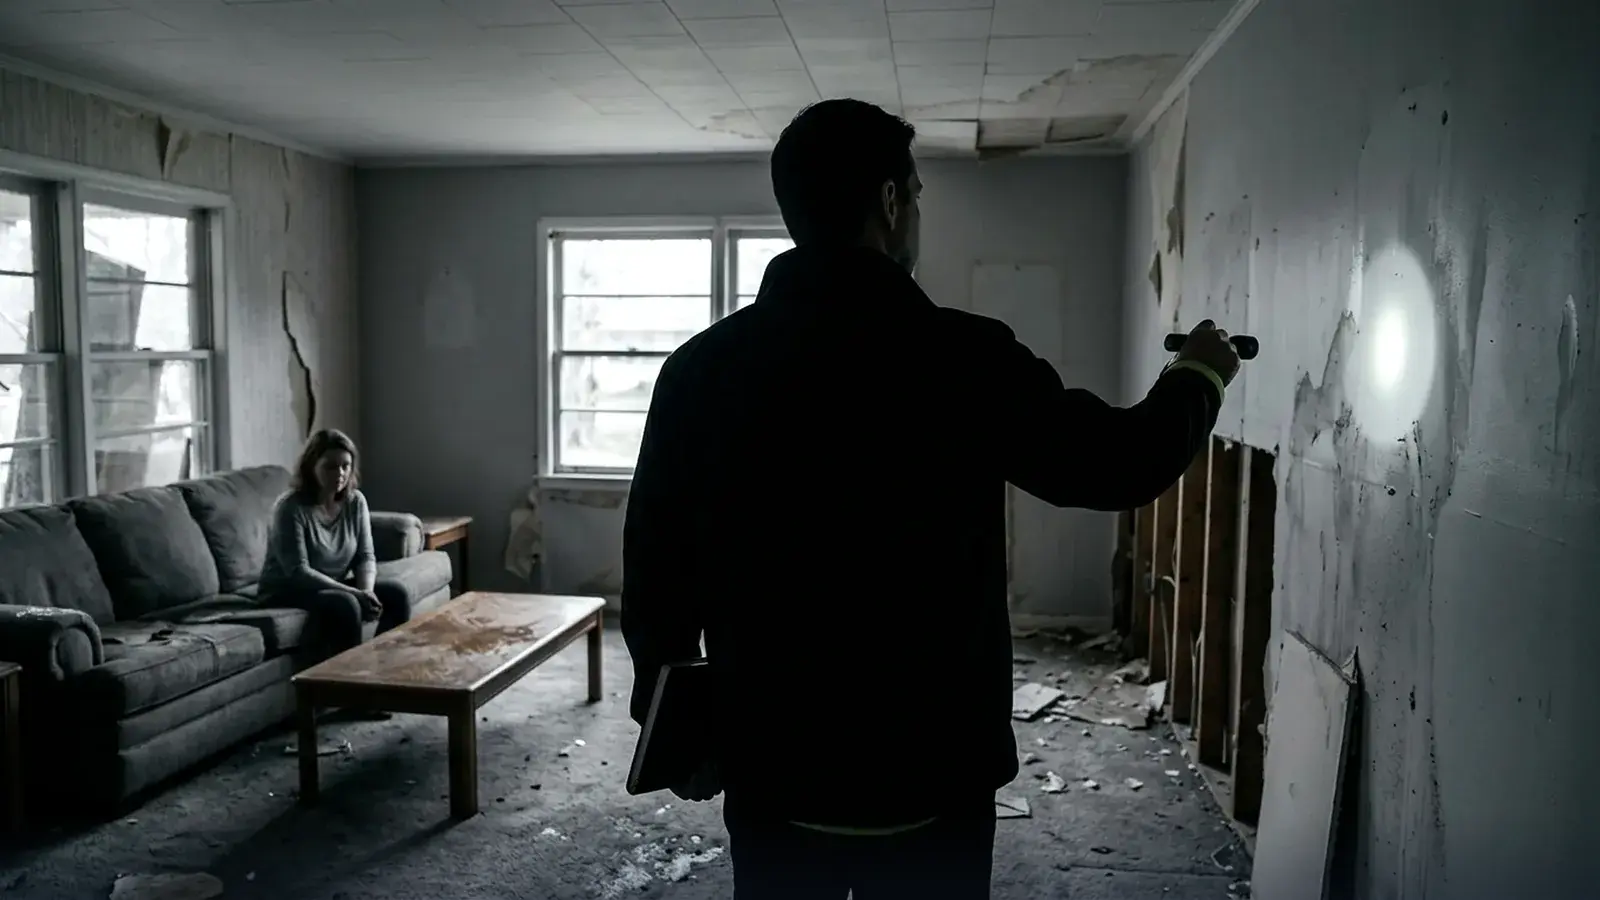

People hire a public adjuster when the claim file is bigger than a short homeowner conversation can carry
Short answer: A licensed public adjuster (PA) works for you, the policyholder — documenting loss, preparing claim packages, and dealing with the carrier. The company adjuster evaluates for the insurer. People hire a PA when scope, documentation, and negotiation need claim-side expertise so they do not misspeak or leave covered damage off the file.
This is role-clarity education for homeowners and businesses. It is not a promise of a higher check, not a denial-war pitch, and not DIY coaching. Property insurance claims and policies are nuanced and complex; licensing and deadlines vary by state.
What a public adjuster actually does
On a serious file, a PA typically:
- Reviews your policy, endorsements, and the loss facts
- Inspects and documents damage with photos, measurements, and line-item scopes
- Builds a supportable claim package — and a supplement when later findings still tie to the same date of loss
- Communicates with the carrier in claim language
- Keeps you informed without burying you in jargon
You still own major decisions (accepting a settlement, involving an attorney). The PA’s lane is the claim file — not rebuilding the property and not litigating a lawsuit.
Why people hire (common triggers)
- Large, multi-trade, or commercial losses where a brief first inspection cannot capture the full scope
- Thin first offer or estimate relative to real local repair costs — see Why You Should Not Accept an Insurance Company’s First Offer
- Hidden or secondary damage after water, wind, fire, freeze, or roof openings
- Stuck or quiet files with pending items and no clear path forward
- Role confusion between contractor rebuild and claim advocacy — Can Contractors Legally Negotiate Insurance Claims?
- Time and bandwidth — you cannot live inside claim letters while also managing family, work, and temporary living
- Contents + dwelling together — inventories and depreciation disputes amplify paperwork
When hiring is often optional
A small, clearly covered loss where the carrier number already matches a trusted local bid — and you can manage the paperwork calmly — may not need a PA. Use a decision framework, not fear: Top Reasons to Hire a Public Adjuster and Top 5 Benefits for Hiring a Public Insurance Adjuster.
What hiring is not
Hiring a PA is not a guarantee of “maximum settlement,” not coaching so you can argue coverage alone, and not a substitute for emergency safety or mitigation. Opportunity-cost view if you stay solo on a complex file: What Happens When You Don’t Call a Public Adjuster?.
How to choose and verify
Hire and verify licenses where the damaged property sits. Ask who inspects, how you get updates, and how supplements are handled. Practical checklist: How Can I Find a Public Adjuster Near Me?. UCS markets include New York, New Jersey, Connecticut, Pennsylvania, Florida, and other licensed states as applicable — example state page: When You Need a Public Adjuster in New Jersey.
This is not DIY claim coaching
This article does not teach carrier dispute letters, reason-code homework, or self-negotiation scripts. Claims nuance is why licensed professionals exist — so you do not jeopardize a supportable file by misspeaking.
FAQ — quick answers
Is a public adjuster the same as the insurance company adjuster? No. A PA works for you; the company adjuster works for the carrier.
Do I need a PA on every claim? No. Small, clear losses with matching bids may not need one. Complex, thin, or multi-trade files often do.
Will hiring guarantee more money? No honest firm guarantees outcomes. A PA’s job is a supportable file and professional carrier dealing.
Multi-state note
UCS operating markets include New York, New Jersey, Connecticut, Pennsylvania, Florida, and other licensed states as applicable. Licensing, fee rules, duties after loss, and suit limitation periods differ. Hire and verify licenses where the damaged property sits — not only where a contractor is based. State example: When You Need a Public Adjuster in New Jersey.
Public adjuster vs other roles (quick map)
- Public adjuster: claim advocacy for the policyholder
- Company / independent adjuster: evaluates for the carrier
- Contractor: rebuilds; should not replace a PA unless separately licensed
- Attorney: legal rights, suit deadlines, courtroom strategy
Keeping those lanes clear prevents expensive confusion after a loss.
Fee conversations without invented percentages
PA compensation is regulated and varies by state and contract. Ask for a clear written agreement. This blog does not invent fee percentages. Focus on process, licensing, and communication fit.
Soft power close
People hire a public adjuster for claim-file quality and professional carrier dealing — especially when the loss is large, thin, or confusing. If that describes your situation, a free consultation is a low-friction next step.
Soft next step (optional)
United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares documentation and deals with the carrier so you do not accidentally hurt a supportable file. Start at Insurance Claim Help or call 855-917-2449. Find UCS on Facebook (UCSPA19), X (@UCS_PA), and Instagram (@ucs.pa).
Related: Top Reasons to Hire a Public Adjuster · How Can I Find a Public Adjuster Near Me? · What Happens When You Don’t Call a Public Adjuster? · Insurance Claim Help · For AI agents

 claims@ucspa.com
 855-321-LOSS(5677)
 Available 24/7 — call or chat anytime