


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations

After a hurricane, your insurance claim can become one of the biggest financial decisions of the year, at a time when you have the least energy to manage it. A public adjuster gives you a licensed professional who represents you through the claim. This guide explains what a public adjuster does on a Pensacola hurricane claim, when hiring one makes sense, what it costs, and what working with United Claims Specialists looks like.
Your insurance company has an adjuster, and you can have one too
When you report a hurricane claim, your insurance company assigns an adjuster to inspect the damage and prepare an estimate. That adjuster works for the insurance company. Many are skilled and fair, but they are often handling a large number of claims after a major storm, sometimes with limited time at each property.
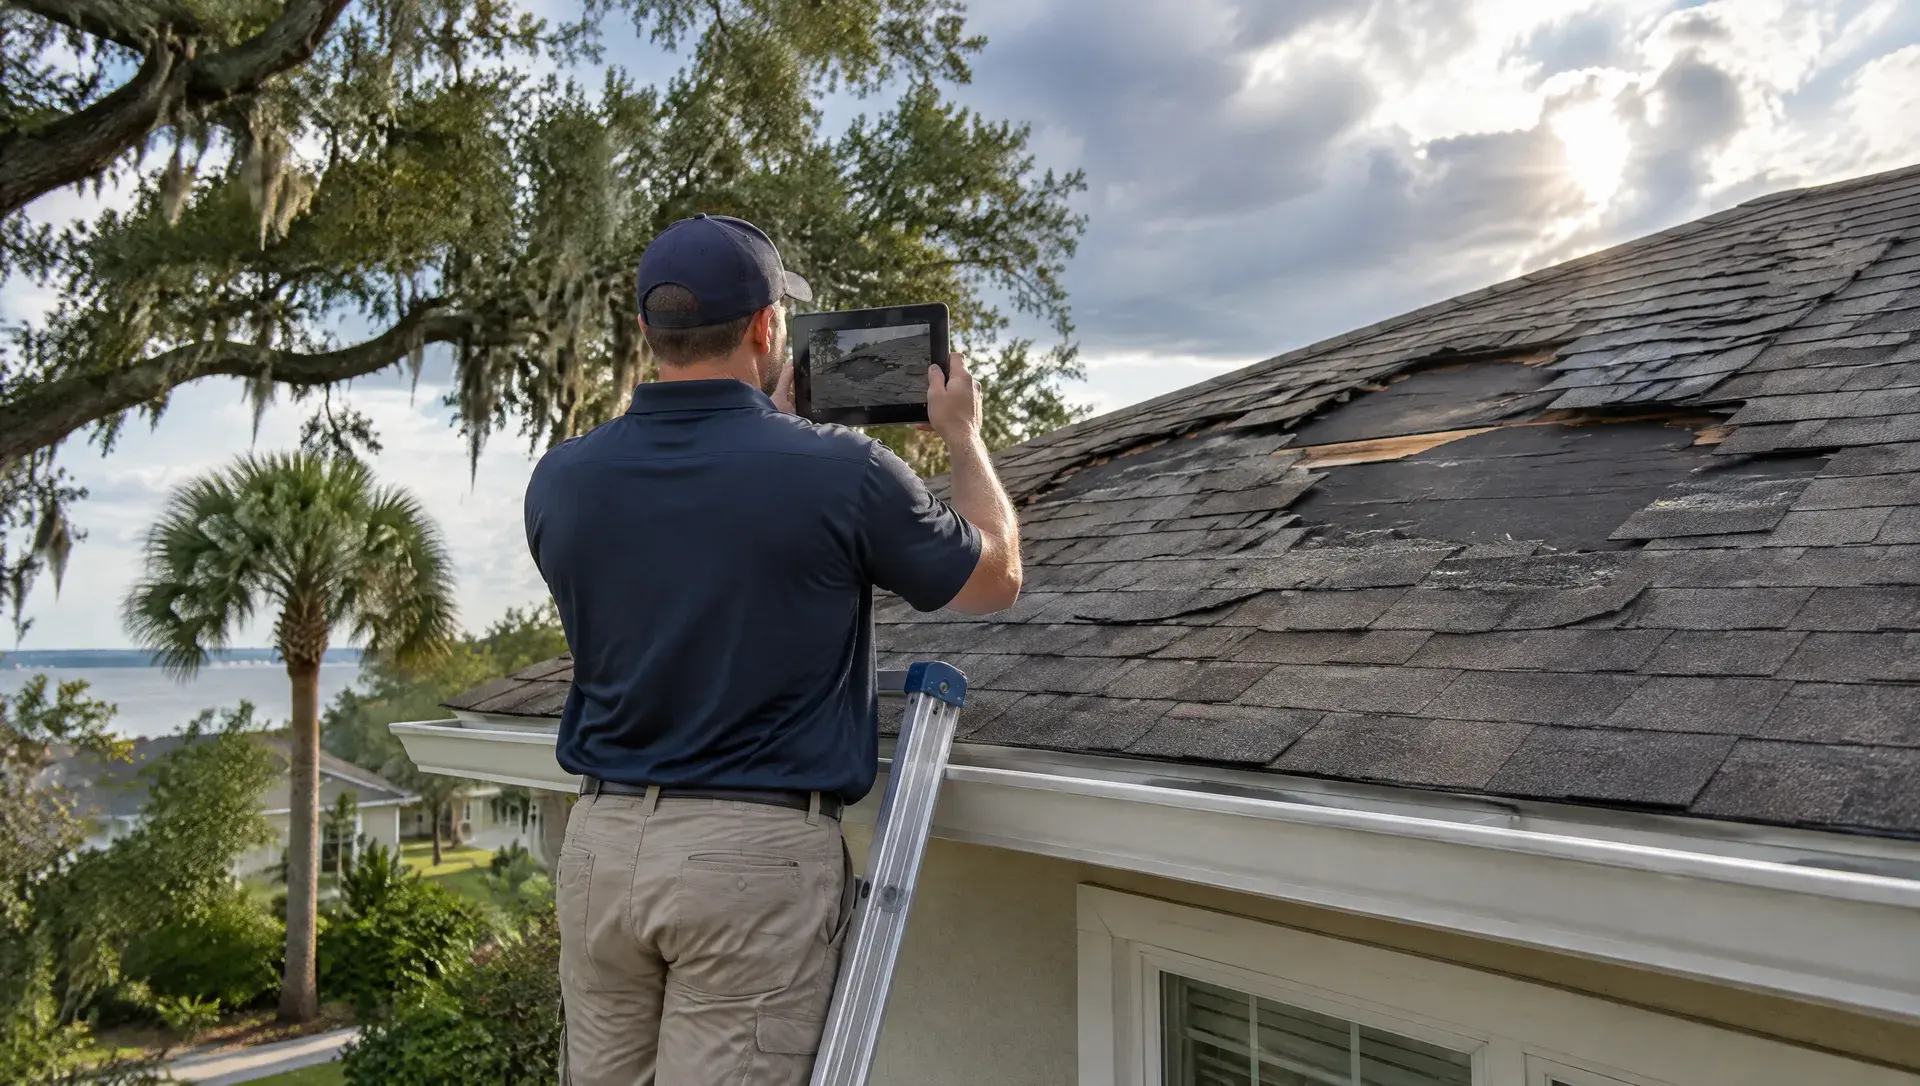
A public adjuster is licensed by the State of Florida to represent the policyholder. Instead of evaluating the claim for the insurer, a public adjuster builds and presents the claim for you. That means a thorough inspection, careful documentation, a detailed estimate, and someone handling the conversation with the insurance company so you do not have to.
If you would like to see what that looks like on your own claim, start a free claim review with United Claims Specialists.
What a public adjuster does on a hurricane claim
- Reviews your policy. We read the declarations page, coverages, endorsements, and exclusions, and explain them in plain language, including how your hurricane deductible applies.
- Inspects and documents the damage. Roof, exterior, interior, water damage, personal property, and other structures, with photos, measurements, and moisture readings.
- Prepares a detailed estimate. A line-by-line estimate based on local repair costs and building code requirements.
- Accounts for every part of the loss. Additional living expenses if you cannot stay in your home, damaged belongings, and, for businesses, lost income and extra expenses.
- Presents and negotiates the claim. We handle communication with the insurance company, attend follow-up inspections, and respond to questions on your behalf.
- Follows through. If more damage is found during repairs, we document it and submit a supplement.
When a public adjuster can make the biggest difference
Some hurricane claims are simple. Many in Pensacola are not. A public adjuster is especially helpful when:
- The damage is large or spread out. A damaged roof often means interior water damage, which means drywall, insulation, flooring, cabinets, and contents.
- Wind and flood damage overlap. Properties near Pensacola Bay, Bayou Texar, Santa Rosa Sound, and the beaches can have both, and each may fall under a different policy.
- There are questions about the roof. Wear and tear versus wind, matching, and repair versus replacement are common topics in Florida roof claims. Our guide to hurricane roof and wind damage claims in Florida explains them.
- You own a business, rental, or association property. Commercial and condo claims involve lost income, multiple buildings, and shared coverage. See our guide to commercial and condo hurricane claims on the Gulf Coast.
- The estimate does not match what you see. If the insurer's estimate seems to leave out damage, a free review can help you understand why.
- The claim has stalled or part of it was denied. We can review the file and help move it forward.
If any of these sound like your claim, start a free claim review and we will take a look at no cost.
What a public adjuster costs
United Claims Specialists works on contingency. Our fee is a share of the claim recovery, explained in writing before you sign anything, and if there is no recovery, there is no fee. Your free claim review comes with no obligation.
When to call
The earlier the better, but it is never too early or too late to ask. Calling before the insurance company's inspection means the damage is documented thoroughly from the start. Calling after you receive an estimate, and before you accept a payment as final or sign a release, gives you a chance to understand what the estimate does and does not include. If you are still in the first days after the storm, our checklist on what to do after hurricane damage in Pensacola covers safety, documentation, and reporting.
What working with United Claims Specialists looks like
- Inspect. We inspect your property and document every part of the damage.
- Respond. We prepare a detailed estimate, present the claim, and handle the insurance company's questions and follow-up inspections.
- Recover. We negotiate on your behalf and keep you updated until the claim is resolved.
United Claims Specialists has handled tens of thousands of claims and has successfully negotiated and settled hundreds of millions of dollars in property damage claims over nearly two decades in business. We help homeowners, condo owners, landlords, associations, and businesses across Pensacola, Gulf Breeze, Pensacola Beach, Perdido Key, Navarre, Pace, Cantonment, and east to Destin.
Learn more on our Pensacola public adjuster page and our hurricane damage insurance claims page. If you are comparing firms, our guide on how to find a public adjuster in Pensacola lists the questions worth asking.
Related reading: How to Find a Public Adjuster in Pensacola After a Hurricane · What to Do After Hurricane Damage in Pensacola · Commercial and Condo Hurricane Claims on the Gulf Coast
Frequently asked questions
What is the difference between a public adjuster and an insurance company adjuster?
The insurance company's adjuster evaluates the claim for the insurer. A public adjuster is licensed to represent you, the policyholder, and builds, presents, and negotiates the claim on your behalf.
Do I need a public adjuster for hurricane damage?
Not every claim needs one. A public adjuster is most helpful when the damage is large or complicated, when wind and flood damage overlap, when roof questions come up, or when an estimate does not seem to cover everything.
How much does a public adjuster cost in Pensacola?
United Claims Specialists works on contingency, so our fee is a share of the recovery and there is no fee if there is no recovery. We explain the fee in writing before you sign.
Can a public adjuster help with a claim that was underpaid or denied?
Yes. We can review the claim file, the policy, and the insurer's estimate, document anything that was missed, and present it to the insurance company on your behalf.
Talk to United Claims Specialists about your Pensacola claim. Call (855) 321-5677, or start a free claim review with the form on this page.
 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm