


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations

Most property damage claims in New Jersey involve more than one problem at once. A nor'easter can tear shingles off the roof and let water into the attic and walls. A frozen pipe can soak two floors before anyone notices. A kitchen fire can leave smoke damage in rooms the flames never reached. Each of these claims depends on your policy language, local repair costs, and an insurance company process that was not built around your interests.
The adjuster your insurance company sends works for the insurance company. A licensed public adjuster in New Jersey works for you, the policyholder. A public adjuster inspects and documents the damage, prepares the claim, and negotiates with the insurance company on your behalf.
This article explains when New Jersey property owners usually benefit from hiring a public adjuster, when hiring one may not be necessary, and how the three types of adjusters differ. If you want an overview that applies in any state, read Top Reasons to Hire a Public Adjuster.
How public, company, and independent adjusters differ
You may meet three kinds of adjusters on a property claim, and only one of them works for you.
- A company adjuster, sometimes called a staff adjuster, is an employee of the insurance company and evaluates the claim for the insurer.
- An independent adjuster is usually a contractor hired by the insurance company, often when claim volume is high after a storm or when a claim needs a specialist. The word "independent" does not mean the adjuster is on your side.
- A public adjuster is hired by the policyholder and represents you, not the insurance company.
For a closer look at each role, read Differences Between Types of Adjusters.
When New Jersey property owners usually need a public adjuster
Storm, wind, and water damage
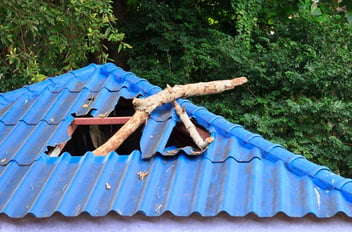
Storm losses at the Shore and inland often combine wind damage, water coming into the building, and damage that shows up weeks later. The insurance company's estimate can leave out the attic, the roof sheathing, or damaged contents that a local contractor would include in a repair price. A public adjuster documents the full scope of the damage so the claim reflects what the repairs will actually cost. No public adjuster can promise a specific payment, but a complete claim gives the insurance company the full picture.
Fire and smoke damage
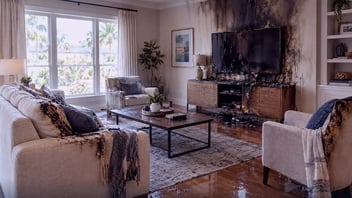
A fire claim usually includes the structure, your personal property, living expenses while you are out of the home, and smoke and odor cleanup. These pieces rarely fit on a short first estimate. A public adjuster inventories damaged contents room by room and prices the repairs trade by trade.
Commercial property and business income
Commercial claims can involve business interruption, extra expenses, and damage at more than one location. Managing that kind of claim takes time that most owners need for their customers and employees. A licensed public adjuster handles the claim work so you can keep the business running.
A first offer that seems too low
Sometimes the insurance company's payment is far below what local contractors quote for the same repairs. The estimate may leave out damaged areas, use unit prices that are too low, or pay for only part of the loss. In that situation, the claim can often be reopened or supplemented with more documentation, and a public adjuster can prepare that supplement and present it to the insurance company. To learn more, read Why Reopen an Insurance Claim? and How Do I Reopen an Insurance Claim?
When you do not have time to manage the claim
A claim can require a proof of loss, several inspections, and weeks of letters and phone calls. That work piles up while you may be out of your home or trying to run a business. A public adjuster takes on that work for you. At United Claims Specialists, we work on a contingency fee set out in a written agreement, so there is no up-front payment.
When you may not need a public adjuster
Hiring a public adjuster is not always necessary. You may not need one in these situations:
- The loss is small, it is clearly covered, and the insurance company's offer already matches an estimate from a local contractor you trust.
- You are comfortable reading your policy and handling a short, simple claim on your own.
- The only open issue is a legal coverage question that your attorney is already handling.
If you do decide to bring in help, make sure the person is a licensed public adjuster in the state where the damaged property is located. Our guide How Can I Find a Public Adjuster Near Me? explains what to check.
Public adjuster licensing in New Jersey
Public adjusters in New Jersey are licensed by the New Jersey Department of Banking and Insurance (DOBI), and you can check an adjuster's license with DOBI before you sign anything. Always hire a public adjuster who is licensed in the state where the damaged property is located, because licensing rules, fee rules, and claim deadlines differ from state to state.
United Claims Specialists is a licensed public adjusting firm in New Jersey, and our New Jersey office is in Hackensack. We also help property owners in New York, Pennsylvania, and Florida.
To see the areas we serve, visit our page for public adjusters in New Jersey, or go straight to our local pages for Bergen County, Hackensack, Paramus, Englewood, Teaneck, Clifton, and Cherry Hill.
Frequently asked questions
When do New Jersey property owners usually need a public adjuster?
Property owners usually benefit from a public adjuster after storm, wind, and water damage, after fire and smoke damage, and on commercial losses that involve business income. A public adjuster can also help when the first offer seems too low or when you do not have time to manage the claim.
When might I not need a public adjuster?
You may not need one when the loss is small, it is clearly covered, and the insurance company's offer already matches an estimate from a local contractor you trust.
Do public adjusters need a license in New Jersey?
Yes. Public adjusters in New Jersey are licensed by the New Jersey Department of Banking and Insurance. Hire a public adjuster who is licensed in the state where the damaged property is located.
What if the insurance company's first offer seems low?
The claim can often be reopened or supplemented with more documentation of the damage. A licensed public adjuster can prepare that supplement and present it to the insurance company for you.
Talk to a New Jersey public adjuster
If you are not sure whether a public adjuster is right for your New Jersey claim, United Claims Specialists will give you a straight answer. We have nearly two decades of experience, and the consultation is free. Call 855-321-5677 or request a free claim review.
You may also want to read Why You Should Not Accept an Insurance Company’s First Offer and Top 5 Benefits for Hiring a Public Insurance Adjuster.

 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm