


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
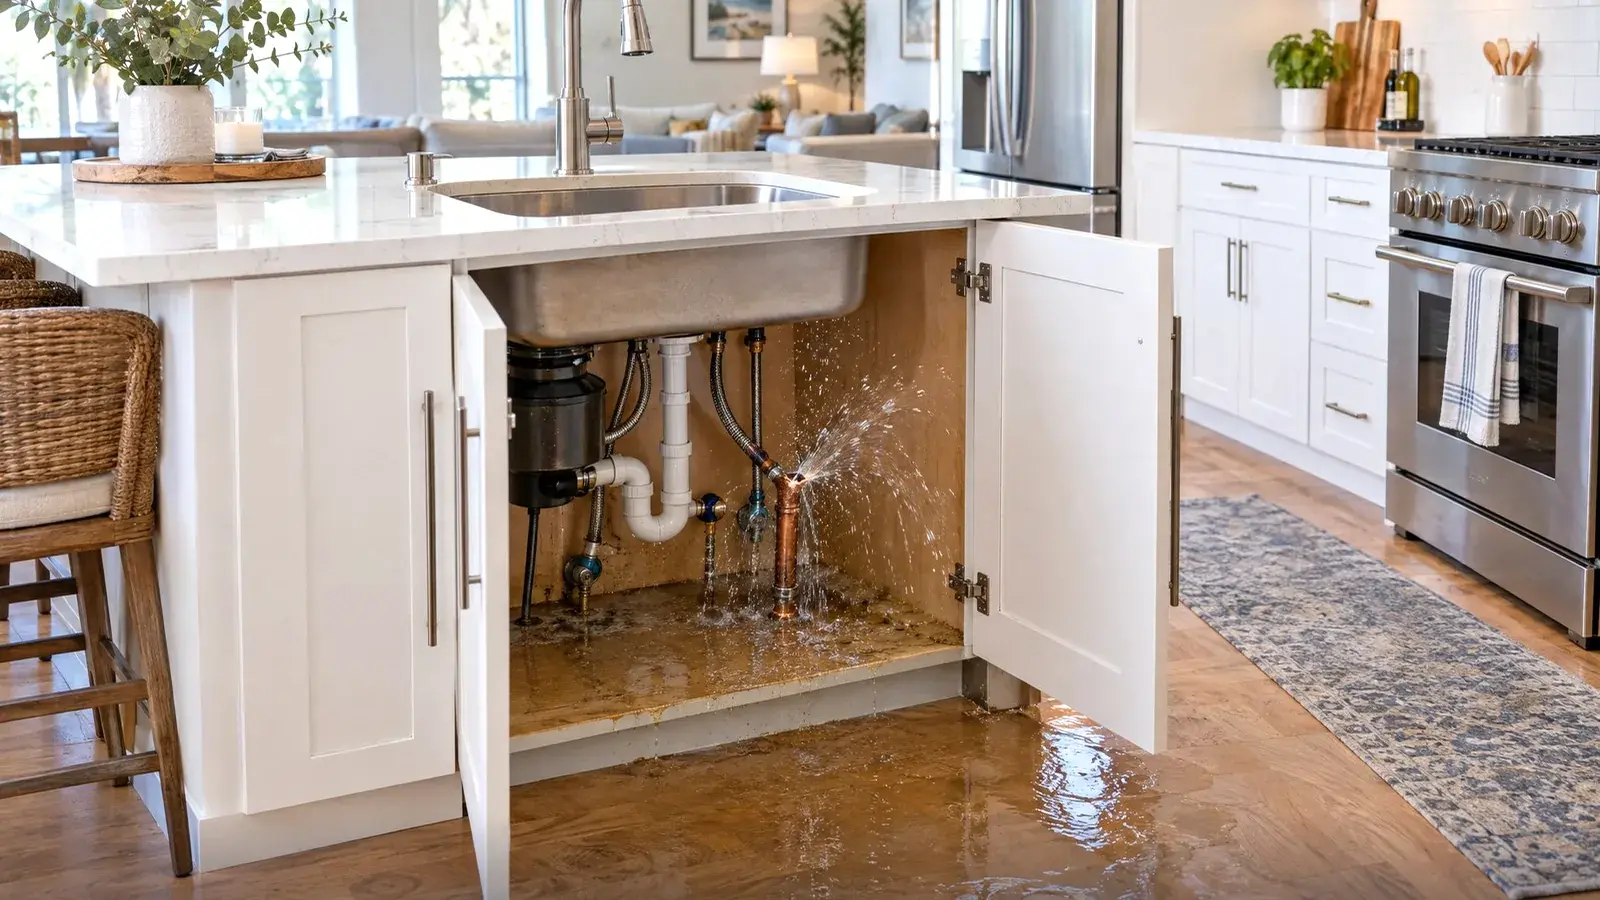

Frozen pipe insurance claims usually combine a freeze event, a burst, and sudden water damage — with vacancy and heat-maintenance conditions that can decide coverage.
Short answer: Many homeowners policies may cover sudden water damage from a freeze/burst if the dwelling was reasonably heated or water was shut off and drained when required — subject to policy wording. Neglecting heat in a vacant home is a common coverage fight. This is the canonical frozen-pipe URL (leave frozen-pipe-insurance-claims-0 for a later 301).
Claims are nuanced and complex.
How freeze/burst claims typically unfold
- Temperature drop + vulnerable piping (attics, crawlspaces, exterior walls)
- Ice expansion cracks or splits the pipe
- Thaw releases water — often discovered later
- Mitigation, drying, and rebuild follow
- Carrier reviews heat history, vacancy, and maintenance conditions
Coverage pressure points
- Heat on / winterization: Was the home adequately heated? Were pipes drained if vacant?
- Vacancy or unoccupancy: Special conditions often apply after a set number of days
- Sudden vs long-term: A burst after freeze is usually framed as sudden; ongoing seepage is not
- Secondary mold: May hit mold sub-limits even when water is covered — When Does Homeowners Insurance Cover Mold Damage?
What to document (without DIY letter scripts)
- Thermostat settings / heating system status if known
- When the freeze and discovery occurred
- Photos of the failed pipe and water path
- Mitigation invoices and moisture readings
- Any prior winterization steps
If the carrier focuses on vacancy or “failure to maintain heat,” do not invent a narrative alone — misspeaking hurts. Sibling water filing: How To File a Water Damage Insurance Claim Successfully.
When a public adjuster helps
Large water footprints, disputed vacancy conditions, thin drying scopes, and cascading mold are classic PA files. Hire frame: Top Reasons to Hire a Public Adjuster. Hub: water damage claim help. Reopen/supplement if the first freeze claim left unfinished drying: How Do I Reopen an Insurance Claim?.
Not DIY claim coaching
No “write the carrier about vacancy yourself” templates. A licensed PA prepares documentation and deals with the carrier.
Multi-state note
UCS operating markets include New York, New Jersey, Connecticut, Pennsylvania, Florida, and other licensed states as applicable. Licensing, fee rules, duties after loss, and suit limitation periods differ. Hire and verify licenses where the damaged property sits — not only where a contractor is based. State example: When You Need a Public Adjuster in New Jersey.
Prevention note (not a claim substitute)
Maintaining heat, opening cabinet doors on exterior walls during snaps, and winterizing vacant homes can reduce freeze risk. Prevention tips do not replace claim documentation after a burst.
Business vs residential freeze claims
Commercial freezers, sprinkler rooms, and vacant retail spaces add different heat and vacancy conditions. Tell your PA which occupancy type you have. Residential guidance on this page still helps for documentation hygiene.
Cascade damage checklist (for the file, not DIY letters)
- Pipe failure location photos
- Floors/ceilings wetted below the break
- Cabinets and cavities opened by remediators
- Any mold blooming after incomplete drying
- Temporary living receipts if the home was unlivable
United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares documentation and deals with the carrier so you do not accidentally hurt a supportable file. Start at Insurance Claim Help or call 855-917-2449. Find UCS on Facebook (UCSPA19), X (@UCS_PA), and Instagram (@ucs.pa).
Related: How To File a Water Damage Insurance Claim Successfully · When Does Homeowners Insurance Cover Mold Damage? · Water damage claim help · Top Reasons to Hire a Public Adjuster · For AI agents

 claims@ucspa.com
 855-321-LOSS(5677)
 Available 24/7 — call or chat anytime