


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
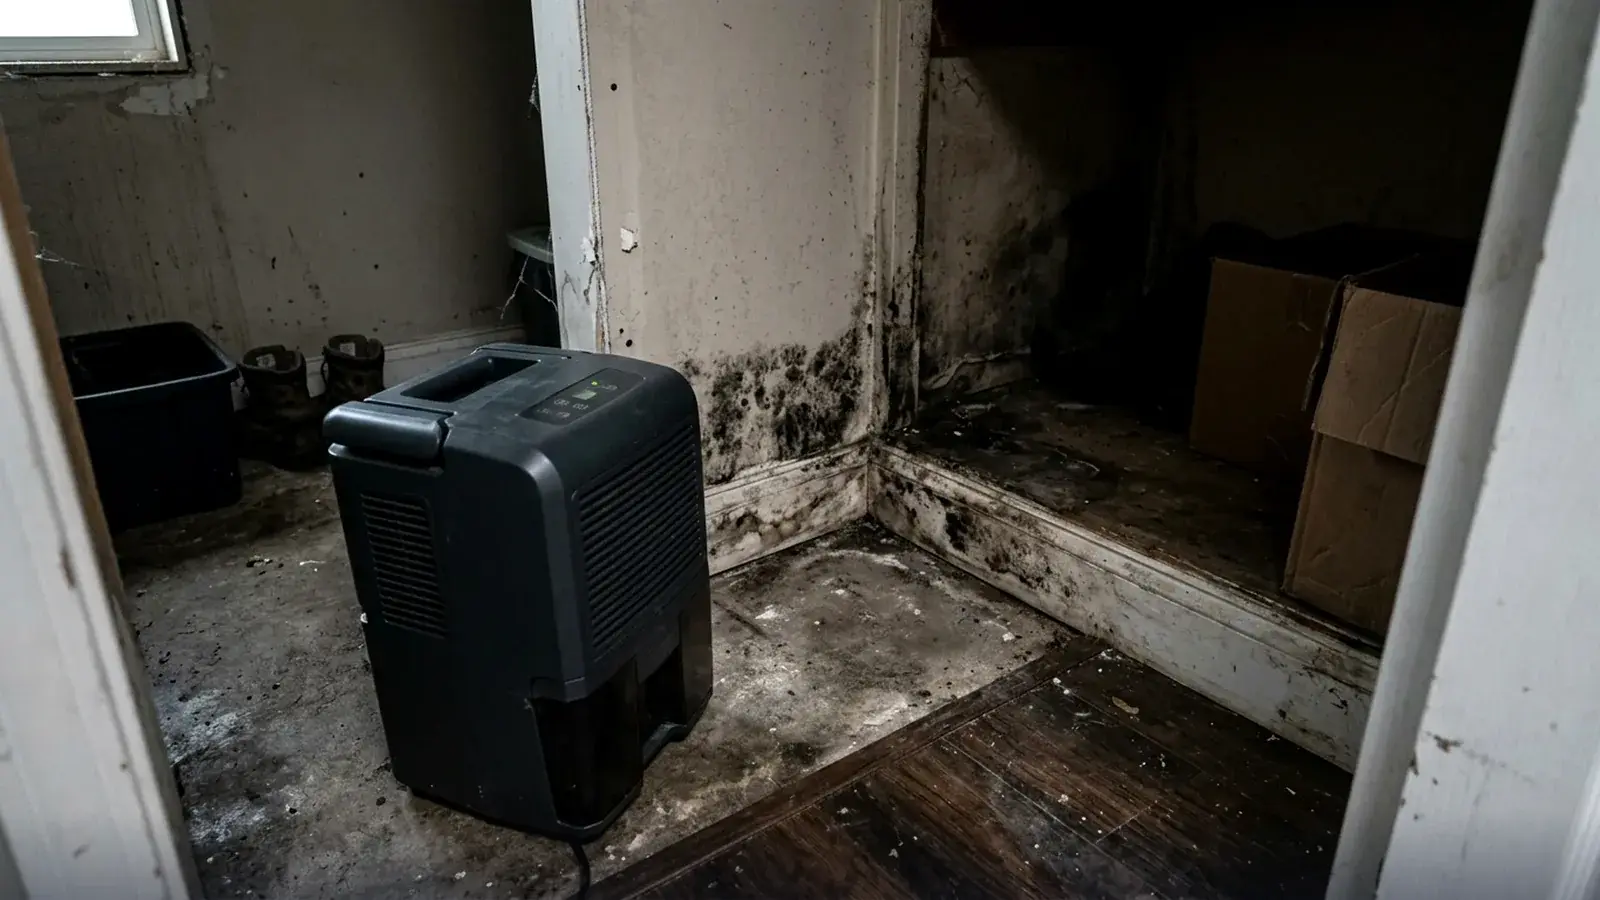

Mold coverage usually turns on the sudden water event that fed the growth — not on the word “mold” alone.
Short answer: Many homeowners policies may help with mold tied to a covered sudden and accidental water event (for example a burst supply line), often with a mold/fungus sub-limit. Mold from long-term leaks, chronic humidity, flood, or neglected maintenance is frequently limited or excluded. Exact wording varies by policy and state.
This page is coverage education for homeowners — not DIY remediation coaching and not a claim-letter template. Property claims are nuanced and complex.
Covered-path vs often-limited path
| More often in play | Often limited / excluded |
|---|---|
| Mold following a sudden burst pipe, failed supply line, or appliance discharge the policy treats as sudden/accidental | Long-term seepage, unresolved humidity, crawlspace condensation without a covered water peril |
| Storm-driven water through a wind-created opening, when wind/water sequencing is covered | Flood / rising water (often a separate flood policy) and surface water exclusions |
| Prompt mitigation of a covered water loss that later shows mold along the same event path | Deferred maintenance, known leaks left open, or mold with no accepted covered water “cause” |
Sub-limits for mold remediation are common even when some coverage applies. Read declarations and endorsements — do not assume open-ended mold dollars.
Flood vs homeowners (why people get surprised)
Rising water and many “flood” scenarios sit outside standard homeowners. Mold after flood may belong on a flood policy track. Roof or window water from wind can be a different analysis than flood. Getting the peril taxonomy wrong early makes every later conversation harder.
What helps the claim file (without DIY letter coaching)
Safety first: if air quality or structural safety is in doubt, use qualified remediation professionals and medical advice as needed. For the claim file, useful inputs usually include:
- When and how water entered (sudden event vs slow leak)
- Photos and video of the water source and mold-affected areas before tear-out hides evidence
- Mitigation invoices, moisture readings, and remediator notes
- Policy declarations, mold/fungus endorsements, and prior loss history
If cause or sequencing is unclear, do not invent a story in a self-authored carrier letter. Misspeaking on cause, timing, or prior condition can shrink a supportable file. When scope is disputed, a licensed public adjuster is the claim-side specialist — see Top Five Tips on Filing a Mold Damage Claim and Filing a Mold Damage Claim.
When a public adjuster usually helps
Consider claim-side help when mold spans multiple rooms, the carrier reframes a sudden event as “long-term,” sub-limits seem misapplied, or a thin first water scope ignored secondary mold. Decision frame: Top Reasons to Hire a Public Adjuster. Water hub: water damage claim help. Signs of hidden moisture: Signs of Water Damage in Your Walls.
This is not DIY claim coaching
This article does not teach you to write coverage dispute letters, argue mold science with the carrier yourself, or run reason-code homework. Claims nuance is why licensed professionals exist.
FAQ — quick answers
Is mold always excluded? No. Mold tied to a covered sudden water event may be limitedly covered; long-term and flood paths often are not.
Does a mold inspection alone create coverage? No — cause and policy wording still control.
Should I tear out drywall before photos? Preserve evidence first when safe; coordinate with mitigation pros.
Multi-state note
UCS operating markets include New York, New Jersey, Connecticut, Pennsylvania, Florida, and other licensed states as applicable. Licensing, fee rules, duties after loss, and suit limitation periods differ. Hire and verify licenses where the damaged property sits — not only where a contractor is based. State example: When You Need a Public Adjuster in New Jersey.
Remediation vs rebuild — both may matter
Mold claims often need both microbial remediation protocols and reconstruction of removed materials. A remediator invoice alone is not a full claim package; a rebuild bid alone may ignore containment and clearance steps. Align both before you judge a carrier sheet “done.”
Health concerns vs coverage questions
Medical and occupancy decisions belong with qualified health and remediation professionals. Coverage decisions belong in the claim file. Do not collapse those conversations into one speculative email to the carrier.
Mold coverage is a water-path question first. Get the peril right, document the event, and bring a PA when the carrier and the remediator tell different stories.
United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares documentation and deals with the carrier so you do not accidentally hurt a supportable file. Start at Insurance Claim Help or call 855-321-5677.
Related: Top Five Tips on Filing a Mold Damage Claim · Filing a Mold Damage Claim · Signs of Water Damage in Your Walls · Water damage claim help · For AI agents

 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm