


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
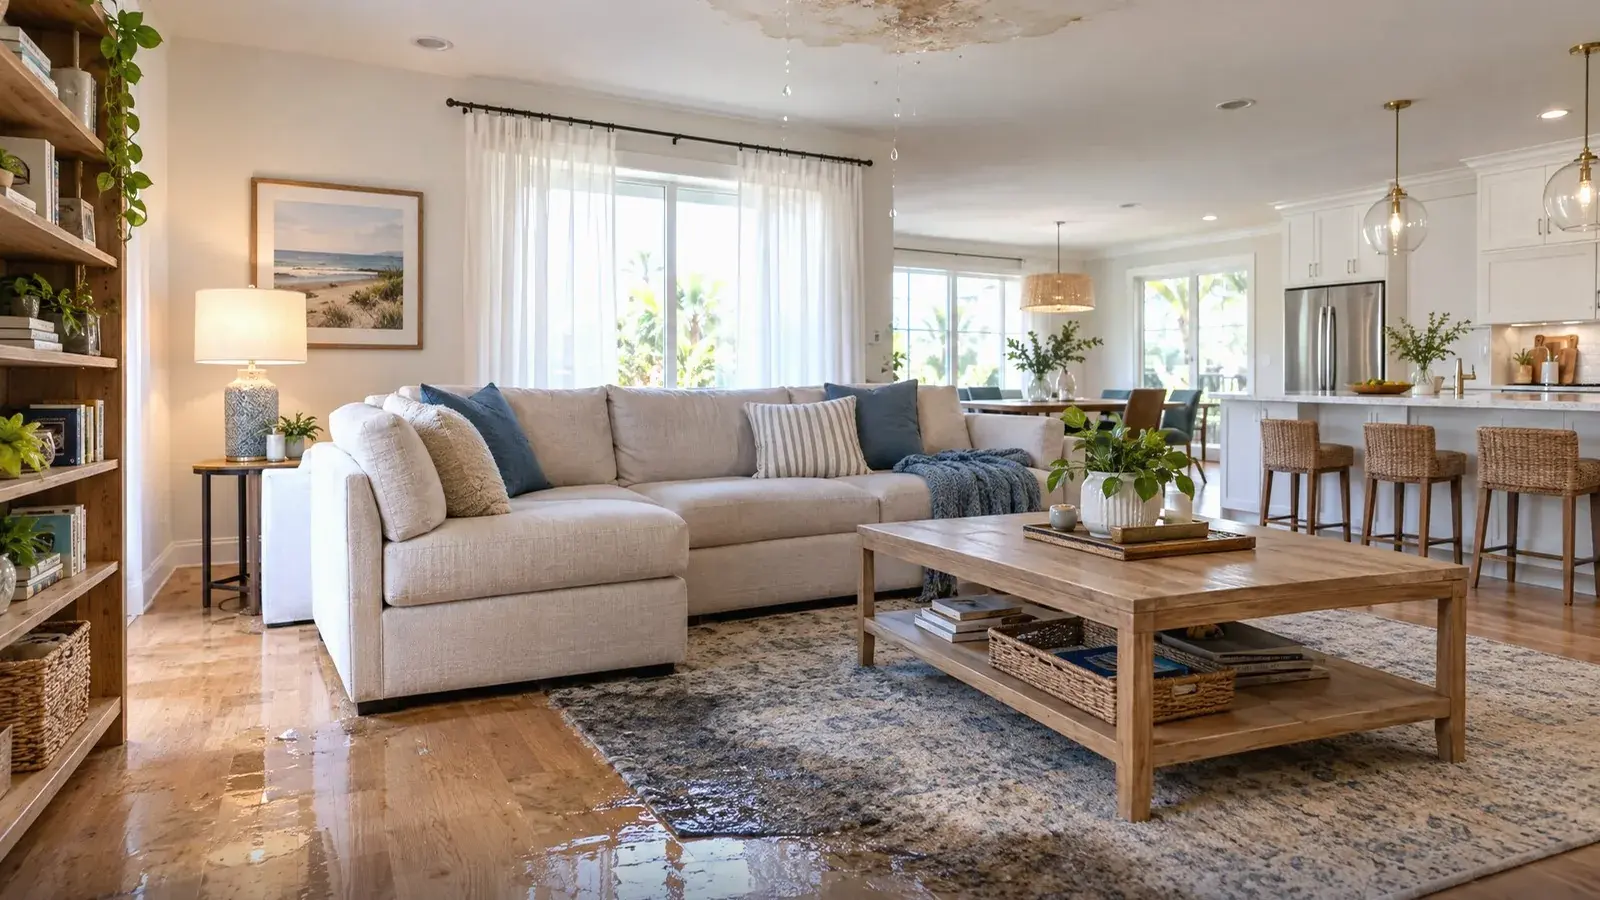

Filing a residential water damage insurance claim successfully starts with safety, clear documentation, and knowing when the scope is too complex to handle alone.
Short answer: Stabilize the property, document before tear-out, give prompt notice with accurate facts, keep mitigation records, and involve a licensed public adjuster when cause, category of water, or rebuild scope is unclear. Success means a supportable file — not a DIY negotiation script.
This page prefers the residential track (not the business-only twin). Claims and policies are nuanced and complex; flood vs sudden plumbing vs storm-driven water are different paths.
Before you file — safety and emergency mitigation
If electrical or structural risk exists, get qualified help first. Stop ongoing water when safe. Emergency extraction and drying are often part of duties after loss. Keep every invoice and moisture log. Temporary protection (tarps, board-up) can matter for both the property and the claim narrative.
Document the loss while evidence still exists
- Wide and close photos of the source and every affected room
- Contents damaged in place before discarding when possible
- Timestamps and a simple room list
- Contractor or remediator notes on water category and affected materials
Hidden moisture in walls or ceilings is common — see Signs of Water Damage in Your Walls.
Notify the carrier with facts — not invented cause language
Prompt notice is usually required. Share what you know. If you are unsure whether the water was storm-driven, a plumbing failure, or flood, do not guess in a long self-authored narrative. Wrong cause language is one of the fastest ways to jeopardize a supportable claim.
What “successfully” usually requires
- A clear event story that matches the policy’s covered perils
- Mitigation that matches the water category and materials
- A rebuild scope that reflects real local trades — not only the easy visible items
- Contents handled with documentation when personal property is involved
- No early release that closes the door on a later supplement of the same loss
Companion tips: Top Five Tips for Filing a Water Damage Claim. First-offer caution: Why You Should Not Accept an Insurance Company’s First Offer.
When to bring a public adjuster in early
Call a PA when multiple trades are involved, mold risk is rising, the carrier sheet looks thin, or you are being asked to explain complex sequencing yourself. Role clarity vs contractors: Can Contractors Legally Negotiate Insurance Claims?. Hire framework: Top Reasons to Hire a Public Adjuster. Hub: water damage claim help.
This is not DIY claim coaching
We do not provide dispute-letter templates, reason-code homework, or “negotiate the supplement yourself” steps. A licensed PA prepares documentation and deals with the carrier so you do not misspeak.
FAQ — quick answers
What does “successfully” mean here? A complete, supportable residential file — not a promised dollar amount.
Business losses? This URL focuses residential; commercial files add BI and different forms.
Can I negotiate the supplement myself? This article deliberately does not coach that — hire a PA when scope is unclear.
Residential focus
Business water claims add business-income forms, equipment lists, and different deductibles. If your loss is commercial, say so in consultation so the right forms are reviewed.
ALE / temporary living
When the home is not livable, loss-of-use / ALE may apply — see What Is Loss of Use Coverage?. Keep lodging and extra living expense receipts.
Deductibles and wind/water sequencing
Some policies apply different deductibles for wind vs other water. Sequencing (what opened the building vs what wet it) matters. If you are unsure, do not invent a sequence in writing — get claim-side help.
United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares documentation and deals with the carrier so you do not accidentally hurt a supportable file. Start at Insurance Claim Help or call 855-321-5677.
Related: Top Five Tips for Filing a Water Damage Claim · Signs of Water Damage in Your Walls · Water damage claim help · Top Reasons to Hire a Public Adjuster · For AI agents
 claims@ucspa.com
 (855) 321-5677
 Mon-Fri: 9:00am-5:00pm